
Premier Foods – Thursday’s Interims should give investors confidence that growth continues and the shares are undervalued

Mark Watson-Mitchell – 10.11.2026
Enriching Life Through Food
(And Investment Portfolios)
This coming Thursday, 12th November, will see the Interim Results being posted by the £1.75bn-capitalised Premier Foods (LON:PFD), covering the 26 weeks period to Saturday, 26th September.
In the last few days, the group’s shares, now 203p, have been nudging gently better, while brokers are suggesting that they could rise another 25% and still be of good value.
The Business
As one of Britain's largest food producers, Premier Foods employs over 4,000 people operating from 13 locations across the country, supplying a range of retail, wholesale, foodservice and other customers with its iconic brands which feature in millions of homes every day.
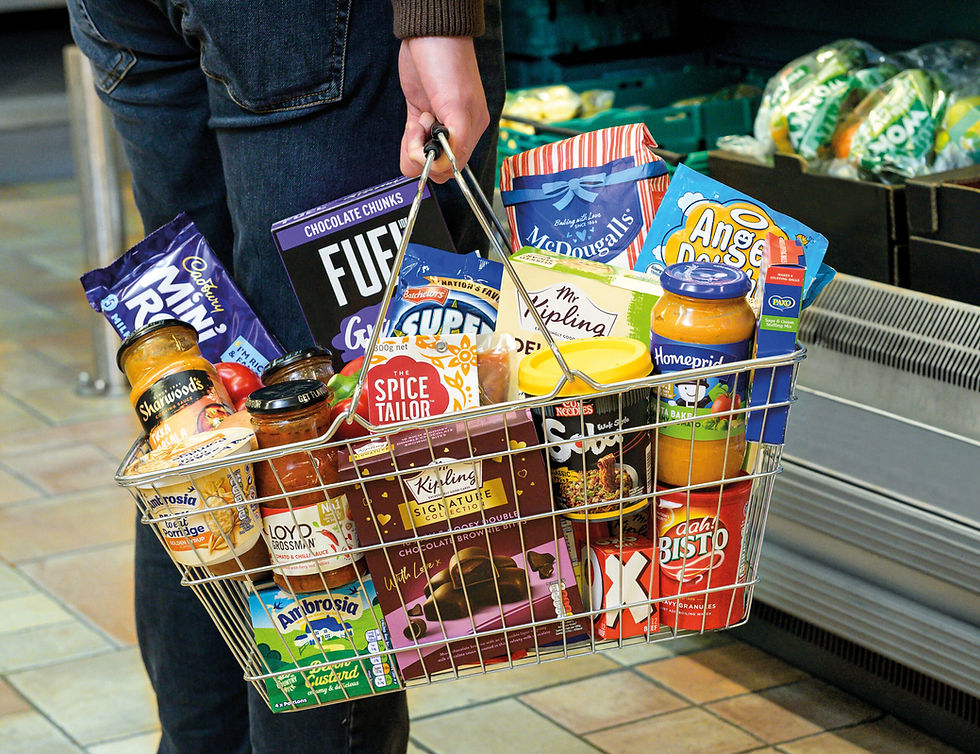
It is the home to some of the nation's best-loved brands, including Ambrosia, Batchelors, Bisto, Loyd Grossman, Mr Kipling, Oxo and Sharwood's.
More recently, it expanded its portfolio of leading brands through acquisitions including The Spice Tailor, FUEL10K and Merchant Gourmet.
The Equity
There are some 869m shares in issue.
The group’s biggest shareholder is Nissin Foods Holdings (25.04%).
Other larger holders include Van Lanschot Kempen Investment Management (6.96%), M&G Investment Management (6.23%), Kempen Orange Participaties (5.25%), JPMorgan Asset Management (UK) (5.07%), Dimensional Fund Advisors (3.78%), Paulson & Co. (2.94%), BlackRock Investment Management (UK) (2.76%), Vanguard Capital Management (2.32%), and Oasis Management (1.80%).
Broker Views
Six analysts closely follow the group, five of whom rate the shares as a Buy, the other as a Hold.
The Consensus Average Target Price is 247p, while the Lowest was 220p and the Highest 290p.
At Shore Capital Markets, analysts Darren Shirley and Clive Black currently have estimates out for the year to end-March 2027, looking for revenues of £1,226m (£1,176m) with adjusted pre-tax profits of £184.5m (£183.6m), creating unchanged earnings of 15.7p, while anticipating a higher dividend of 4.5p (3.4p) per share, with the group halving its net debt to £48.0m (£95.0m).
For 2028, they see £1,273m sales, £194.1m profits, earnings of 16.5p and a 5.4p dividend, while transferring into net cash of £39.0m by the year-end.
In their estimates for 2029, the analysts go for £1,321m revenue, £204.2m profits 17.4p earnings, a 6.5p per share dividend and a massive £120.0m net cash position.
The analysts have previously stated that:
“We see this highly successful proprietary branded British food manufacturer as being fundamentally undervalued (250p would be a fairer base) with considerable scope for medium-to-long term ongoing rating expansion.”
My View
The above SCM analysts are totally right, Premier Foods deserves a far better rating than it is now standing on, with its shares at just 203p they are on just a 12.9 times price-to-earnings ratio.
That should be at least 16 times, the market average, giving them that 250p price tag.
(Profile 29.06.20 @ 67.50p set a Target Price of 101p*)
(Profile 01.11.23 @ 117.50p set a Target Price of 152.75p*)
(Profile 15.07.26 @ 199p set a Target Price of 250p)


Comments